Does Medicare Cover Medical Alert Systems? Life Alert, PERS, and Who Actually Pays
-
October 5, 2026

Reviewed by Austin Farley
Medicare Broker Licensed in KS, AK, AL & 43 other states
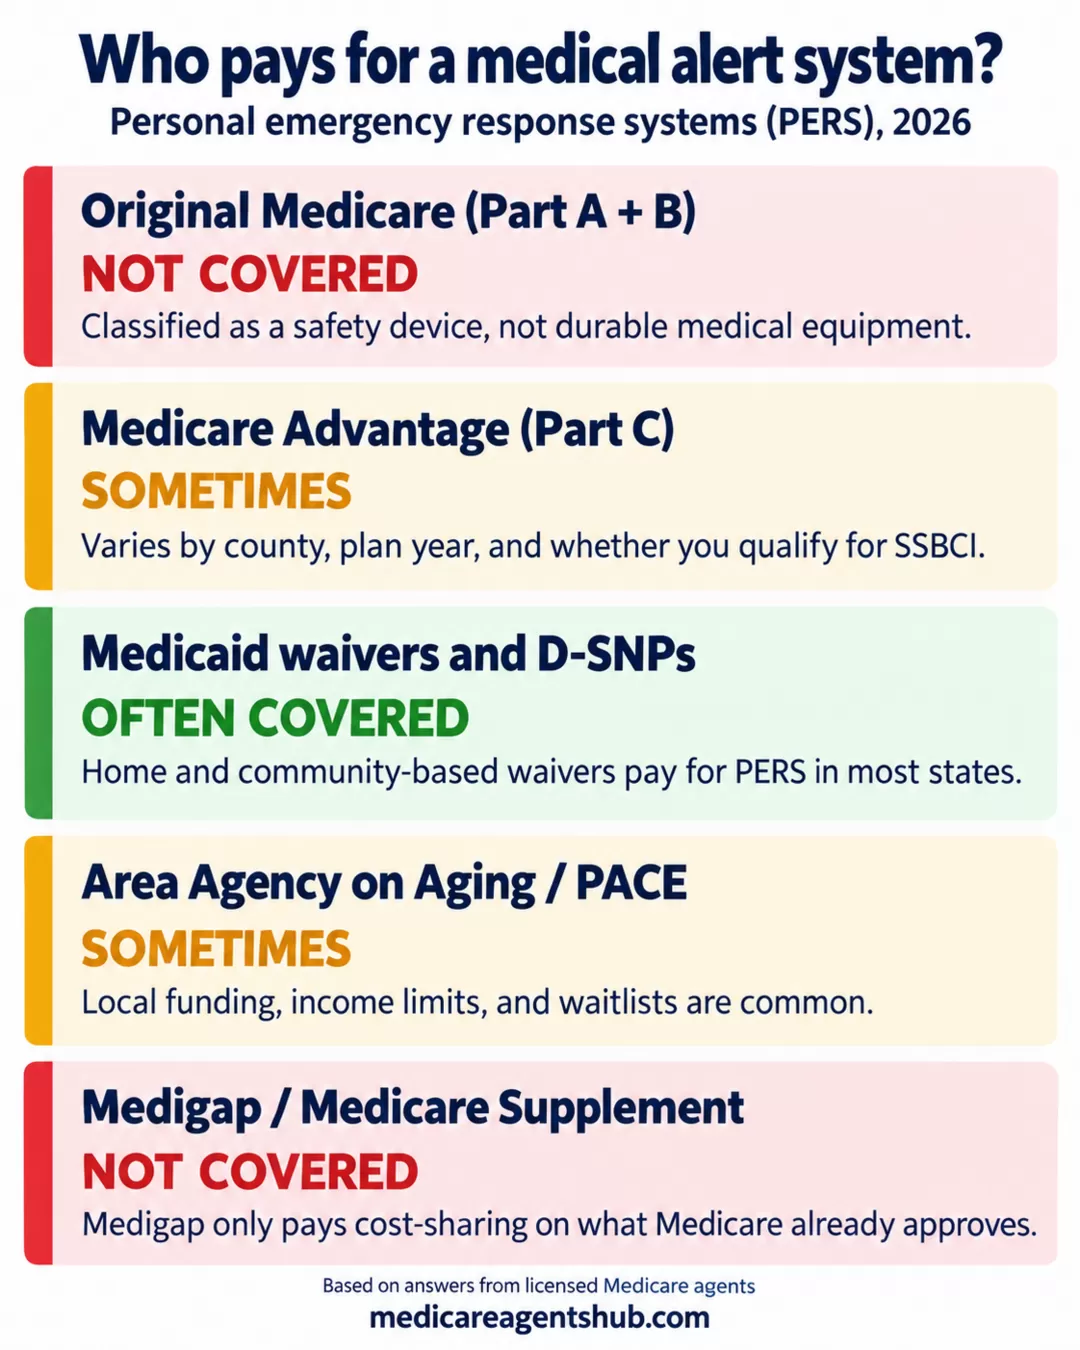
Original Medicare will not buy you a medical alert system. Not the pendant, not the base station, not the monthly monitoring fee. That answer has been consistent for years, and it surprises a lot of people who assume a device designed to save your life after a fall would qualify as medical equipment.
But that is only half the answer. Medicare Advantage plans, state Medicaid programs, and a handful of local aging services do pay for these devices, and the rules for each are different. Here is who actually covers what.
Quick answer: Original Medicare (Parts A and B) does not cover medical alert systems or Life Alert, because Medicare classifies them as safety and convenience devices rather than durable medical equipment. Some Medicare Advantage plans include a personal emergency response system as a supplemental benefit, many state Medicaid waiver programs cover one, and dual-eligible plans cover it more often than standard Advantage plans do. If nobody covers it, expect to pay roughly $25 to $50 a month out of pocket.
Why Original Medicare won't pay for Life Alert or any medical alert system
Medicare Part B pays for durable medical equipment when a doctor prescribes it and it meets a specific test: the item has to be reusable, last at least three years, and be used primarily and customarily to serve a medical purpose in your home. Wheelchairs pass. Hospital beds pass. Oxygen concentrators pass.
A medical alert pendant does not, and the reason is a little frustrating. The device doesn't treat anything. It calls for help. Medicare's DME rules treat that as a safety feature, the same bucket that holds grab bars and stair railings, so the equipment and the monthly monitoring both fall outside Part B.
Doctor's orders don't change it. Agents field this call constantly, and the answer is the same even when a physician writes that the device is medically necessary after a fall.

Does Medicare pay for medical alert systems?
No. Original Medicare Part B covers medically necessary durable medical equipment (DME), things like wheelchairs, hospital beds and such. A medical alert system is usually considered a safety or monitoring device, not a medically necessary piece of equipment.Having said this, there are some Medicare Advantage (Part C) plans, rather than Original Medicare, that do offer coverage for this item. Some of these plans may offer these systems either free or at a discount.
You must check carefully the plan's benefit with your agent, as this coverage, if offered, varies widely among companies.
Which Medicare Advantage plans cover medical alert systems
Part C is where this actually gets interesting. Medicare Advantage plans can offer supplemental benefits that Original Medicare doesn't, and a personal emergency response system (PERS, in plan documents) is one of the more common ones.
Three different buckets are worth knowing:
- Standard supplemental benefits. Some mainstream HMO and PPO plans include a basic in-home PERS device at no extra cost. Availability swings wildly by county, and a plan that offers it in Broward County may not offer it 90 miles north.
- SSBCI. Special Supplemental Benefits for the Chronically Ill let plans offer non-medical items to members with qualifying chronic conditions. Fall-risk devices and home safety items show up here often.
- Chronic and dual special needs plans. C-SNPs and D-SNPs include PERS far more often than general-enrollment plans, because their members are, by design, higher risk.
A fourth path exists on plans that give you an over-the-counter or flex card. Some allowances can be spent on a monitoring device or a fall-detection watch even when the plan doesn't list PERS as a standalone benefit. Read the approved-item list, because those lists are narrower than the marketing suggests.
One thing trips people up more than anything else: the benefit rarely arrives on its own. You have to ask.

Does Medicare cover Life Alert or medical alert systems?
Medicare does not; however, some Medicare Advantage plans offer a Personal Emergency Response button at no cost. You will need to call the company to request they send yours.Who pays for a medical alert system
Does Medicaid cover Life Alert or a medical alert system?
If you qualify for Medicaid as well as Medicare, your odds improve a lot. Most states run home and community-based services waivers built around one idea: keeping people out of nursing homes is cheaper than paying for nursing homes. A $30 monthly monitoring fee is a rounding error against that math, so PERS is a standard covered item in a majority of state waiver programs.
Dual-eligible special needs plans follow the same logic. Agents who sell in dual-heavy markets tend to know exactly which carriers ship a button and which don't.

Does Medicare pay for medical alert systems?
Medical alert systems are often covered with Dual Complete plans and MyCare Ohio plans. With UnitedHealthcare, that is what I’m aware of, as well as with Anthem.Worth checking even if you assume you earn too much: the income and asset limits for Medicare Savings Programs and Extra Help are higher than most people guess, and partial-benefit categories can open the door to a D-SNP.
Outside Medicaid entirely, your local Area Agency on Aging is the underused option. Many run subsidized or donated-device programs funded through the Older Americans Act. Some counties have a waiting list. Some hand out refurbished units the same week. It's worth one phone call.
What a medical alert system costs if nobody covers it
Retail pricing is not terrible, and it has come down as cell-based units replaced landline ones. Typical 2026 ranges:
| Setup | Monthly monitoring | Upfront cost |
|---|---|---|
| In-home base station (landline) | $20 to $30 | $0 to $50 |
| In-home base station (cellular) | $30 to $40 | Device fee common |
| Mobile GPS pendant or watch | $35 to $50 | $50 to $150 |
| Automatic fall detection | Add $10 to $15 | Usually bundled |
Life Alert itself doesn't list prices on its website. You call for a brochure and a quote, so hold that quote up against the ranges above before you sign.
Two things to watch before you sign. First, contract length. Month-to-month is now the norm across most of the market, but a few brands still push multi-year agreements, and cancellation terms on those have generated complaints for a long time. Second, equipment ownership. Some companies lease you the hardware, which means a return shipment and a fee if you cancel.
If you have money left in a health savings account from your working years, monitoring fees may qualify as a medical expense with a letter of medical necessity from your doctor. Ask your HSA custodian first, since they set the documentation bar.
The rest of the home safety gap
Medical alert systems are one item in a broader category Medicare leaves alone. Grab bars, ramps, walk-in tubs, widened doorways, and stairlifts all sit on the wrong side of the same line: Medicare pays for equipment you bring into the house, not changes you make to the house.

Are home modifications (like stairlifts) ever covered by Medicare for safety reasons?
No, Original Medicare (Parts A and B) does not cover stairlifts or other home modifications — even if your doctor recommends one for safety or to prevent falls. Medicare considers stairlifts/chairlifts to be permanent changes to your home, not medical equipment. Only certain durable medical equipment, called DME, is covered. This includes items like wheelchairs, walkers, hospital beds, and patient lifts that help you move from bed to chair. These items are reusable and meant mainly for medical needs. Because a stairlift is attached to your stairs or walls, Medicare does not cover it.*Alternatives for funding if you're exploring options for a stairlift:
-Check Medicaid (varies by state; some waivers or programs cover home modifications for eligible low-income individuals).
-Look into VA benefits (for veterans with service-connected disabilities).
-Explore local aging agencies, nonprofit programs, grants, or manufacturer financing.
Families dealing with cognitive decline hit this wall hardest. A pendant only works if the person wears it and understands what the button does, which is why door alarms, GPS trackers, and the round-the-clock supervision families of wandering dementia patients need end up being a separate and much more expensive conversation.
Don't choose a plan for the button
Here is where agents get emphatic. A medical alert system costs about $360 a year retail. A narrow provider network, a high specialist copay, or a drug formulary that doesn't carry your medication can cost you multiples of that in a single year.
Pick the Medicare Advantage plan that covers your doctors and your prescriptions. If the plan you were going to choose anyway happens to throw in a PERS device, take it. If it doesn't, buy the device yourself for the price of a streaming bundle and keep the better medical coverage. Choosing a plan for the extras rather than the core coverage is one of the more expensive mistakes people make during enrollment.

Why do some agents push Medicare Advantage plans over Medigap? Should I be skeptical?
It's fair to ask why a particular plan is being recommended, and you should always feel comfortable asking questions. A good Medicare agent should take the time to understand your doctors, prescriptions, budget, and healthcare needs before making a recommendation. Neither Medicare Advantage nor Medigap is the right choice for everyone, so the recommendation should be based on what fits your situation rather than a one-size-fits-all approach.Common questions
Does Medicare cover Life Alert specifically?
No. Life Alert is a brand of personal emergency response system, and Original Medicare excludes the whole category regardless of manufacturer. Medicare Advantage plans that cover PERS almost always contract with a specific vendor, and it is usually not Life Alert. You take the plan's device or you buy your own.

Does Medicare cover Life Alert or medical alert systems?
Original Medicare usually won't pay for medical alert systems like Life Alert. They're not considered medically necessary equipment under the program. That said, some Medicare Advantage plans include extra benefits like this, and a local broker can help you see what options you actually have nearby.Will Medigap cover it if Original Medicare doesn't?
No. Medigap pays deductibles, copays, and coinsurance on services Medicare already approves. If Medicare pays nothing, Medigap pays nothing.
What about an Apple Watch with fall detection?
Consumer smartwatches are not covered by Original Medicare either. A few Medicare Advantage plans have offered wearables through wellness allowances, and some flex card programs let you apply funds toward one. Check the approved-item list rather than assuming.
My doctor wrote a prescription. Does that help?
Not with Original Medicare. It can help with an HSA reimbursement, a Medicaid waiver application, or an Advantage plan's SSBCI eligibility review, so hang onto it.
How do I find out whether my plan includes one?
Check the Evidence of Coverage document under supplemental benefits, not the marketing flyer. Or ask a licensed agent to pull the benefit grid for the plans available in your ZIP code. A local agent can usually answer in under five minutes, and the agents answering this question on Medicare Agents Hub come from markets all over the country.

Does Medicare cover Life Alert or medical alert systems?
Some Medicare Advantage plan carriers do cover Life Alert and/or medical alert systems. Specific plans within the carrier do carry those systems, and others do not.This is why it's important to speak with a qualified agent to get the answers you need.