Medicare 101: Helping You Understand the Basics to Protect Your Future
-
Last Updated September 14, 2026
One of the biggest decisions you'll face at retirement is how to handle your healthcare coverage, and that's where Medicare comes in.
This Medicare basics guide walks beginners through what Medicare is, what it covers, when you're eligible, how to enroll, and how much it costs.
What Is Medicare?
Medicare is the federal health insurance program designed to provide coverage for:
-
Individuals who have reached age 65 or older
-
Certain younger people with disabilities
-
Those diagnosed with End-Stage Renal Disease (ESRD), which is permanent kidney failure that requires dialysis or a transplant
In 1965, the passage of the Social Security Amendments established a comprehensive program of health insurance for individuals aged 65 and older, along with a separate program (Medicaid) for people with limited income. Today, Medicare is divided into four parts, each covering different aspects of your healthcare.
The Four Parts of Medicare Explained
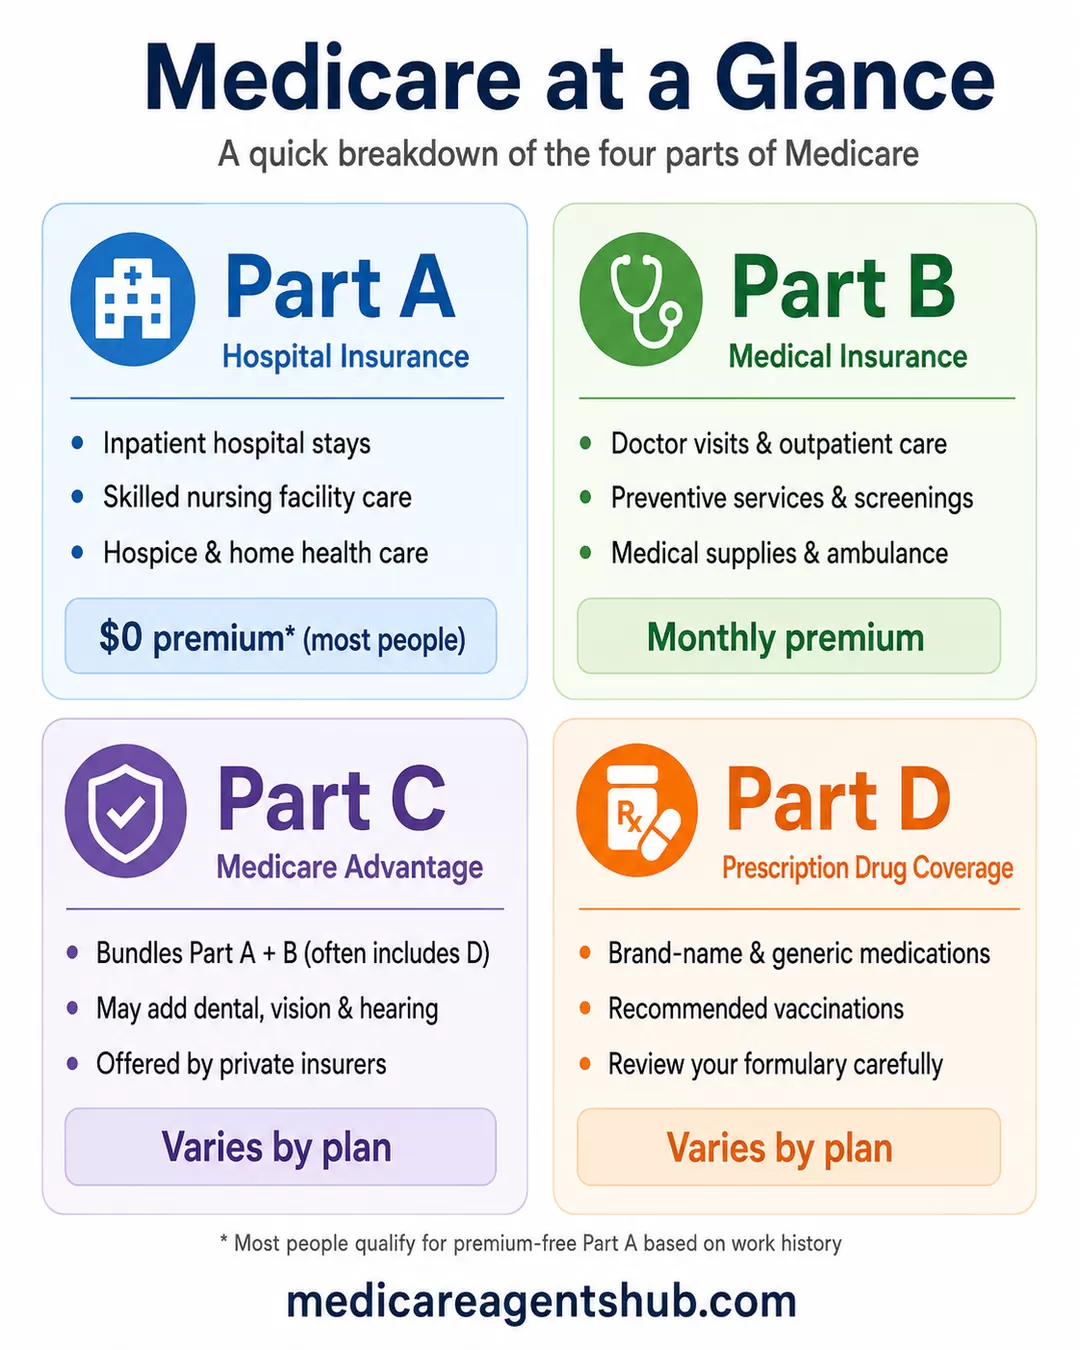
Here is the whole program on one screen before we go part by part.
| Part | Also called | What it covers | What it costs in 2026 |
|---|---|---|---|
| Part A | Hospital insurance | Inpatient hospital stays, skilled nursing facility care, hospice, some home health care | Premium-free if you or your spouse paid Medicare taxes for 40 quarters. $1,736 deductible per benefit period |
| Part B | Medical insurance | Doctor visits, outpatient care, preventive screenings, lab work, medical equipment | From $202.90 per month, plus a $283 annual deductible |
| Part C | Medicare Advantage | Parts A and B bundled through a private plan, usually with drug coverage and extras like dental and vision | Varies by plan, and you keep paying your Part B premium |
| Part D | Prescription drug coverage | Brand-name and generic prescriptions, plus many recommended vaccines | Varies by plan, with income-based surcharges at higher incomes |
Medicare Part A (Hospital Insurance)
Part A covers the costs associated with inpatient care.
-
Inpatient hospital stays
-
Skilled nursing facility care
-
Hospice care
-
Some home healthcare
Medicare Part B (Medical Insurance)
Part B covers outpatient and preventive care.
-
Doctor visits and outpatient care
-
Medical supplies and equipment
-
Preventive services and screenings
-
Mental health services and ambulance services
Medicare Part C (Medicare Advantage)
Medicare Advantage plans are offered by private insurers approved by Medicare. They bundle Part A and Part B coverage into a single plan, and many also include prescription drug coverage (Part D) along with extras like dental, vision, and hearing. These plans often have network restrictions, so it's important to understand the trade-offs. Learn more about how a Medicare agent can help you navigate Advantage plans.
Medicare Part D (Prescription Drug Coverage)
Medicare Part D is offered through private insurance companies and helps cover the cost of your prescription medications.
-
Helps cover the cost of prescription medications, including both brand-name and generic drugs
-
Includes coverage for many recommended vaccinations
-
Plans and formularies vary, so learn how a local agent can help you find the right drug plan

Is Original Medicare or Medicare Advantage better? Why do you recommend one over the other?
Neither Original Medicare nor Medicare Advantage is inherently "better"; the best choice depends on your health, budget, and preference for provider choice vs. bundled benefits, with Original Medicare offering nationwide doctor freedom but needing Medigap for extras/limits, while Medicare Advantage provides all-in-one plans (often with $0 premiums, dental/vision, drug coverage) but uses provider networks and requires an out-of-pocket max (MOOP) for protection. Recommend Original Medicare for travel/provider choice, and Medicare Advantage for lower premiums/extra benefits if you're okay with networks.When Am I Eligible for Medicare?
Your first chance to sign up for Medicare is during your Initial Enrollment Period (IEP), which begins three months before the month you turn 65, includes your birthday month, and ends three months after, making it a seven-month window total.
For example, if your birthday is March 12th, your IEP runs from December through June. If you sign up in the first three months (December, January, or February), your coverage starts on March 1st. If you enroll during your birthday month or in the three months after, your coverage will start the first day of the month after you sign up, so waiting can delay when your benefits begin.

I'm turning 65 soon, when can I enroll in Medicare?
That's a Great question!Most people can enroll in Medicare when they turn 65. Your Initial Enrollment Period is a 7-month window that begins 3 months before your birthday month, includes your birthday month, and ends 3 months after.
Example: If your birthday month is May, your enrollment window runs from February through August.
Here's a little known fact: If your birthday is on the 1st day of the month, Medicare treats you as if you turned 65 the month before, so your coverage can start one month earlier!
If you’ve been receiving Social Security (or Railroad Retirement) benefits for at least 4 months before your 65th birthday, you’re usually automatically enrolled in Medicare Parts A and B, and your Medicare card is mailed to you.
If you’re still working and covered by an employer health plan, your timing may be different, and you may be able to delay Part B without a penalty.
If you’re turning 65 soon, it’s a good idea to review your situation early so you understand your options and avoid surprises.
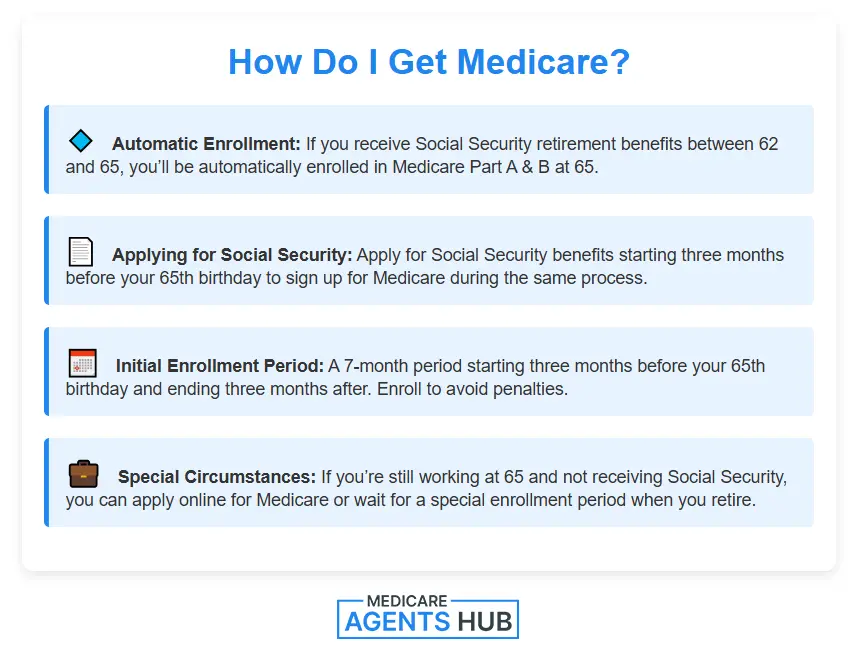
How Do I Get Medicare?
Enrolling in Medicare is fairly simple, and there are several paths depending on your situation:
-
Automatic Enrollment: If you are already receiving Social Security retirement benefits at least four months before you turn 65, you'll be enrolled automatically in Medicare Part A and Part B when you reach 65.
-
Applying for Social Security: If you apply for Social Security benefits three months before your 65th birthday or later, you can sign up for Medicare during the same process.
-
Initial Enrollment Period: This 7-month window begins three months before you turn 65 and ends three months after your birthday month. Enrolling on time is crucial to avoid late enrollment penalties.
-
Special Circumstances: If you're still working at 65 with employer coverage, you may be able to delay Part B without penalty, but this generally only works if the plan comes from an employer with 20 or more employees and your coverage is considered creditable. Retiree coverage, COBRA, and small-employer plans usually do not qualify, so check how your specific employer coverage works with Medicare before you delay. Once you retire or lose that coverage, you'll qualify for a Special Enrollment Period to transition to Medicare.

I'm turning 65 next month; what are the first steps I should take regarding Medicare enrollment?
If you don't have employer coverage and you plan on enrolling in Medicare, the first thing you'll want to do is enroll in Medicare Part A and Part B. This is done through the Social Security Administration. You can enroll online (the quickest way) or by phone or in-person appointment at your local SS branch. To enroll online, you'll need to have a login.gov or id.me account, so if you don't already have one, you can create one. You can do that here: https://www.ssa.gov/myaccount/ You'll need a mobile phone that has a valid email address you can access as well as receive sms messages to set up your account for the first time as they verify your identity using your phone's camera (does not work using a pre-paid phone). Once you have your account set up, go to https://www.ssa.gov/medicare/sign-up and click the first box "Sign up for Medicare".What Does Medicare Cover?
While specifics can vary based on your plan, Medicare Advantage plans are required to provide coverage that is at least actuarially equivalent to Original Medicare (in plain terms, the plan has to cover at least as much overall as Original Medicare does), though how you access those services may differ (for example, through network restrictions or prior authorization). Certain services may also have limitations, such as being available only in specific facilities or for patients with particular conditions.
Medicare coverage is determined by three key factors:
-
Federal and state laws establish the basic framework for Medicare coverage.
-
National coverage decisions made by Medicare dictate whether certain services are covered under the program.
-
Local coverage decisions, handled by companies processing Medicare claims in each state, determine the medical necessity of services within their respective areas.
In general, Medicare Part A covers:
-
Inpatient care in hospitals
-
Skilled nursing facility care
-
Hospice care
-
Home health care
Medicare Part B covers two types of services:
-
Medically necessary services: Diagnostic and treatment services meeting accepted medical standards.
-
Preventive services: Healthcare aimed at preventing or detecting illnesses early, including flu shots and a wide range of screenings and wellness visits.
Part B also covers clinical research, ambulance services, durable medical equipment, mental health care, and various outpatient programs. Under Original Medicare, you're free to see any Medicare providers (doctors, specialists, or hospitals that accept Medicare) anywhere in the country, with no network restrictions, and most preventive services come at no cost when you use a provider who accepts Medicare assignment. On a Medicare Advantage plan, the same protection generally applies to in-network providers.

I need home health care after my surgery, but Medicare denied coverage. What are my appeal rights?
To start the appeal process, you first have 120 days from the time coverage was denied to file for a redetermination of coverage. I recommend you start by reaching out to your doctor to provide more details as to why home health care is medically necessary for you after surgery. If coverage is still denied you can move on to the next step of the appeals process which is for reconsideration and allows for an independent review which all details will be provided for that if redetermination is denied.How Much Does Medicare Cost?
If you're wondering about how much Medicare costs, you should know that Medicare requires a monthly premium and a portion of the costs for each covered service. Unlike many private insurance plans, Original Medicare has no annual cap on out-of-pocket expenses unless you have supplemental coverage like a Medicare Supplement (Medigap) policy or a Medicare Advantage Plan.
In 2026, Part A is premium-free if you or your spouse paid Medicare taxes for at least 10 years (40 quarters of work). If you don't meet that work requirement, you can still get Part A by paying a monthly premium. Either way, Part A carries a deductible of $1,736 per hospital admission per benefit period. Part B premiums start at $202.90 per month (subject to income-based adjustments), and the annual deductible is $283. Part D and Medicare Advantage Plan premiums vary by plan and may also be subject to income-based surcharges. These amounts are adjusted annually. Visit medicare.gov for the most current figures.
If you go with a Medicare Advantage plan, it must include an annual limit on what you pay out of pocket for in-network Part A and Part B services. Medicare sets a maximum for that limit each year and plans can choose to set theirs lower, but it's worth knowing that not every cost counts toward that out-of-pocket maximum (prescription drug spending under Part D, for example, is tracked separately).
Staying informed about updates to Medicare premiums and deductibles is essential for budgeting your healthcare expenses effectively. You must also continue paying your Part B premium to remain enrolled in a Medicare Advantage Plan.

Why do some seniors end up paying lifelong penalties for Medicare Part B or Part D?
Because they missed their initial enrollment window and didn't have qualifying coverage to fill the gap. For Part B, if you don't sign up when you're first eligible and don't have creditable coverage through an employer, you get hit with a 10% penalty for every 12 month period you could have had it but didn't. That penalty sticks with you permanently, added to your premium every month for as long as you have Part B. Part D works similarly but calculates it differently, roughly 1% of the national base premium for each month you went without creditable drug coverage. These penalties exist to discourage people from waiting until they get sick to sign up, but a lot of folks get caught simply because they didn't understand the rules or thought they could delay without consequences.Need Help Understanding Your Medicare Benefits?
Medicare eligibility typically starts at age 65, but enrollment periods and coverage options vary. Be sure to enroll during your Initial Enrollment Period to avoid penalties. Knowing the costs and available supplemental coverage options can help you plan for your healthcare expenses effectively.
Because Part B and Part D late enrollment penalties are permanent, getting your timing right the first time matters more than almost any other Medicare decision you'll make.
For personalized guidance on navigating Medicare options, we always recommend seeking help from a local Medicare insurance agent licensed in your state. If you'd also like free, unbiased counseling, every state runs a State Health Insurance Assistance Program (SHIP) staffed by trained volunteers who don't sell insurance. You can find your state's program at shiphelp.org.
Frequently Asked Questions
What is a simple definition of Medicare?
Medicare is a federal health insurance program primarily for people aged 65 and older, individuals with certain disabilities, and those with end-stage renal disease. It provides coverage for various medical services, including hospital stays, doctor visits, and prescription drugs, helping beneficiaries afford essential healthcare.
What is covered under Medicare Part A?
Medicare Part A, also known as hospital insurance, covers essential inpatient hospital care, skilled nursing facility stays, hospice care, as well as lab tests, surgeries, and home health care. It ensures beneficiaries have access to necessary hospital and related services, providing financial protection for these vital healthcare needs.
What is covered under Medicare Part B?
Medicare Part B covers medically necessary services and preventive care. This includes services essential for diagnosing or treating medical conditions according to accepted medical standards. Additionally, Part B includes preventive healthcare such as flu shots and screenings to prevent illnesses or detect them early when treatment is most effective.
What is the Medicare Advantage Plan?
A Medicare Advantage Plan (Part C) offers an alternative to Original Medicare through private insurance plans approved by Medicare. These plans provide all Part A and Part B benefits, often including additional coverage such as prescription drugs, dental, vision, and hearing services. Medicare Advantage Plans typically have network restrictions and may require copayments or coinsurance.

What is the biggest disadvantage of Medicare Advantage?
The biggest disadvantage is that Medicare Advantage can limit which doctors and hospitals you can use and make it harder to get certain care approved. It often means more prior authorizations, denials, and network hassles than Original Medicare.What is covered under Medicare Part D?
Medicare Part D provides prescription drug coverage, helping beneficiaries afford necessary medications. Private insurance plans approved by Medicare offer Part D coverage. Covered medications include both brand-name and generic drugs prescribed by a doctor. Coverage specifics vary between plans, so it's essential to review the formulary to ensure your medications are included.
Which parts of Medicare are required, and which are optional?
None of it is mandatory in a strict sense, but the rules make waiting expensive. Part A is close to automatic: if you're drawing Social Security at 65, you're enrolled, and it's premium-free for most people. Part B is optional on paper, though going without it while you have no other creditable coverage triggers a late enrollment penalty that sticks to your premium for life. Parts C and D are genuinely your choice, but Part D carries its own permanent penalty once you've gone 63 days or more without drug coverage.
How can I benefit from a local Medicare insurance agent?
Finding a local Medicare insurance agent is a smart step in retirement planning. Agents help you select policies tailored to your unique needs. Independent Medicare brokers are particularly helpful because they work with multiple insurers, allowing them to compare coverage options and find the best fit for your medical requirements and budget.