How Annuities Play a Role in Medicare Planning
-
Last Updated October 19, 2026

Reviewed by Ty Chastain
Medicare Agent Licensed in MS, AL, AR & 42 other states
When preparing for retirement, many people focus on Social Security, 401(k)s, and IRAs. There's another financial tool that plays a growing role in the conversation: annuities. While annuities are not part of Medicare itself and don't affect your eligibility to enroll, they can have a direct impact on what you pay for your Medicare coverage, especially when it comes to premiums, out-of-pocket costs, and how you qualify for related programs like Medicaid.
Understanding how annuities interact with Medicare can help retirees make smarter financial decisions and avoid unexpected costs.
Quick answer: Annuities don't change your Medicare eligibility or your coverage, but they can change what you pay. Payouts that count as ordinary income raise your MAGI, and a high enough MAGI triggers IRMAA surcharges on your Part B and Part D premiums two years later. How you time and structure those payouts decides whether that happens.
What Are Annuities?
An annuity is a financial product sold by insurance companies. It provides a stream of income, either for a set period or for life, in exchange for a lump sum or a series of payments. Annuities are often used to create a predictable source of income in retirement.
There are different types of annuities; fixed, variable, indexed, and immediate, each with its own rules and benefits. Some annuities allow your money to grow tax-deferred, while others are designed to start paying out income immediately.

What role do annuities play in retirement planning?
In our practice, we view annuities as serving three primary roles in retirement planning: storage, growth, and income. All three can be accomplished using fixed annuities, depending on the client’s needs and stage of retirement.In the storage role, funds are placed into a fixed annuity that earns a predetermined rate of interest. These products are often used as a conservative alternative to traditional savings vehicles. In many cases, the interest rate can exceed what is typically available through bank CDs or bonds, while also providing principal protection. Many annuity contracts also allow for limited withdrawals each year, giving retirees access to funds if needed.
A growth annuity—often a Fixed Indexed Annuity (FIA)—offers the potential for market-linked returns while protecting the principal. These products are tied to a market index, allowing the account to participate in a portion of market gains. However, because they are designed with downside protection, the contract owner will not lose principal due to market declines. This makes them appealing to individuals who want growth potential but are uncomfortable with market risk.
The third role is income. Income annuities are designed to provide guaranteed lifetime income, often covering both spouses. Because the income cannot be outlived, they are sometimes referred to as a personal pension plan. For many retirees, this creates a dependable monthly deposit similar to Social Security. This strategy can be especially valuable for individuals who are concerned about running out of money or who want a predictable income stream to cover essential living expenses.
When used appropriately, annuities can help address several key retirement risks—market volatility, longevity risk, and income stability. By structuring annuities around storage, growth, and income, retirees can create a balanced strategy that protects assets, allows for potential growth, and most importantly provides reliable income.
Is There Such a Thing as a "Medicare Annuity"?
No. A lot of people shop for a "Medicare annuity" as though it were a single product, but these are two separate things sold by two separate systems. Medicare, the federal health insurance program for people 65 and older (and some younger individuals with disabilities), does not offer, sell, or manage annuities. Annuities come from private insurance companies.
The two still interact, and that's where retirees get caught off guard: the income you receive from annuities can directly affect your Medicare costs.
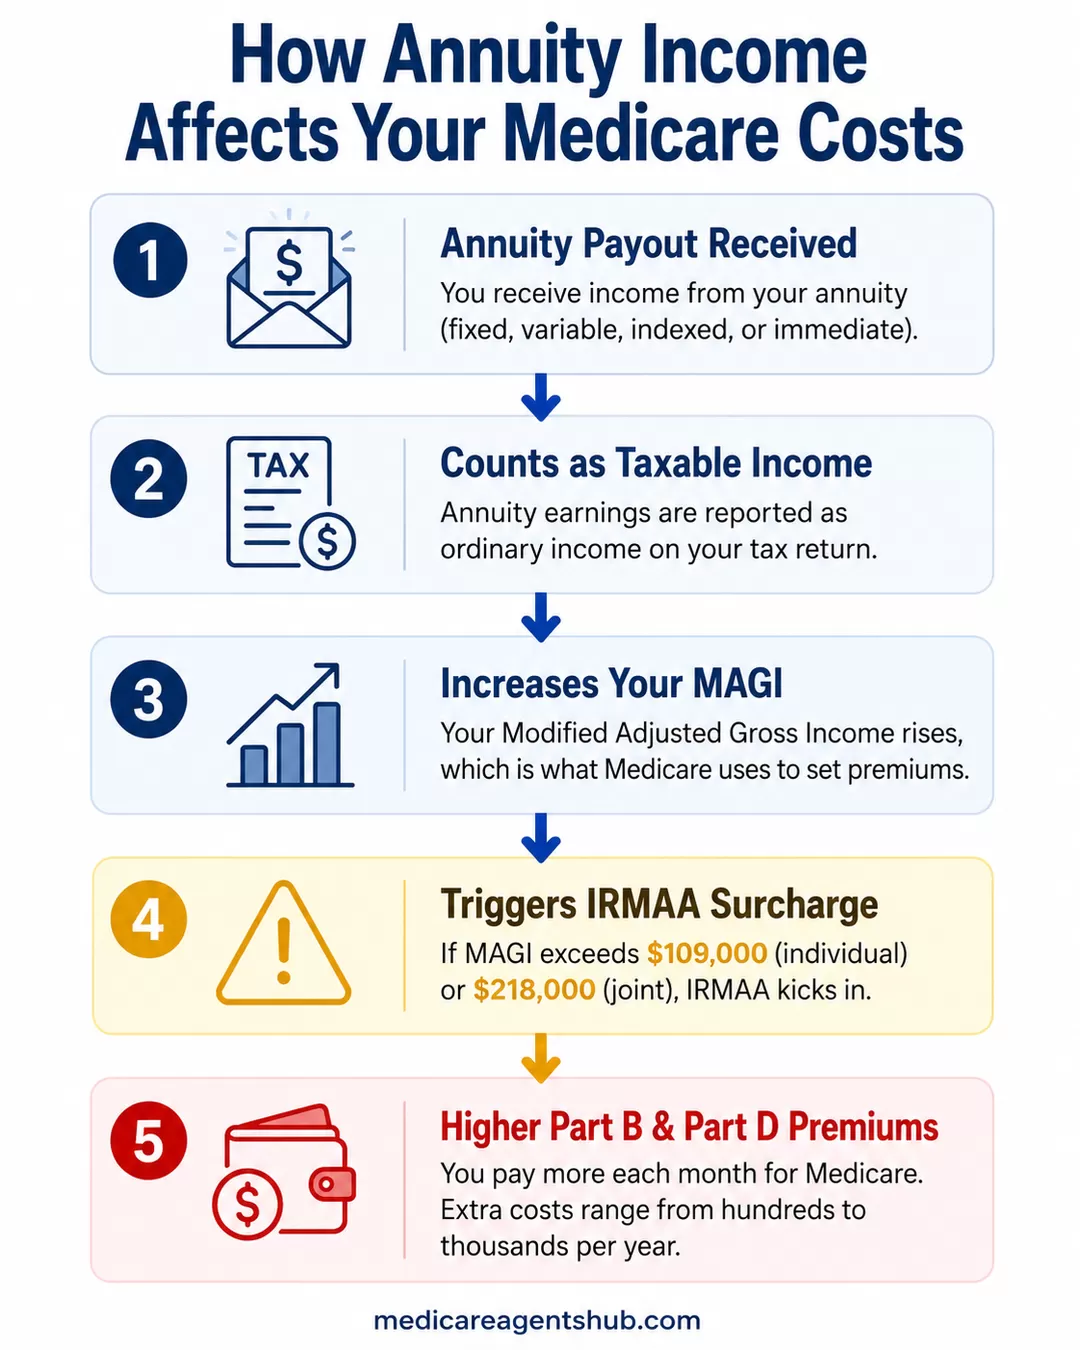
Most notably, annuity income can increase your Modified Adjusted Gross Income (MAGI), which the government uses to determine how much you'll pay for Medicare Part B and Part D premiums.
How Annuity Income Affects Medicare Premiums
Medicare premiums aren't the same for everyone. If your income is above a certain level, you'll be required to pay more through something called the Income-Related Monthly Adjustment Amount (IRMAA).
Here's how it works:
-
The Social Security Administration looks at your tax return from two years prior to determine your current year's Medicare premiums.
-
If your MAGI is above $109,000 for individuals or $218,000 for couples filing jointly in 2026, you'll pay a higher monthly premium for Medicare Part B (doctor visits, outpatient care) and Part D (prescription drugs). The standard Part B premium for 2026 is $202.90 per month.
-
Annuity payouts, depending on the structure, may count as ordinary income and be included in your MAGI.
Do Annuity Payments Count as Income for Medicare?
Whether a payout counts, and how much of it counts, depends on where the money came from. A qualified annuity was funded with pre-tax dollars, usually inside an IRA or 401(k), so the whole payment is taxable and all of it lands in your MAGI. A non-qualified annuity was funded with money you already paid tax on, so only the earnings portion is taxable and the return of your original principal is not. Same size check, very different effect on your premiums.
What Counts Toward MAGI for IRMAA, and What Doesn't
For IRMAA purposes, MAGI is your adjusted gross income plus any tax-exempt interest. That is a wider net than most retirees expect, and it's the reason an annuity payout can cost you more than the tax bill on it alone.
Counted in your MAGI:
- The taxable portion of annuity and pension payments
- Withdrawals from traditional IRAs, 401(k)s, and 403(b)s
- Deferred compensation, in the year it's actually paid out to you
- Wages and self-employment income
- Capital gains, dividends, and taxable interest
- Tax-exempt municipal bond interest, even though you owe no income tax on it
- Rental and royalty income
- The taxable share of your Social Security benefits, which can run as high as 85% of what you collect depending on your other income
Not counted:
- Return of your own principal from a non-qualified annuity
- Qualified Roth IRA distributions
- HSA withdrawals used for qualified medical expenses
- Life insurance death benefits paid to a beneficiary
- The non-taxable share of your Social Security benefits
One more thing worth knowing before you look at the numbers: this test gets re-run every year. IRMAA is not a permanent label. Social Security checks a fresh tax year each January, and the bracket thresholds themselves shift with inflation, so a single large payout raises your premiums for one year and then falls off. That's why the way Medicare recalculates IRMAA annually matters as much as the payout itself.
2026 IRMAA Brackets and What a Payout Actually Costs
Here's what the 2026 brackets look like. Social Security uses your 2024 MAGI to set what you pay in 2026:
| 2024 income, individual return | 2024 income, joint return | 2026 Part B premium | 2026 Part D surcharge |
|---|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 | No surcharge |
| Over $109,000 up to $137,000 | Over $218,000 up to $274,000 | $284.10 | +$14.50 |
| Over $137,000 up to $171,000 | Over $274,000 up to $342,000 | $405.80 | +$37.50 |
| Over $171,000 up to $205,000 | Over $342,000 up to $410,000 | $527.50 | +$60.40 |
| Over $205,000 and under $500,000 | Over $410,000 and under $750,000 | $649.20 | +$83.30 |
| $500,000 or above | $750,000 or above | $689.90 | +$91.00 |
The Part D amount is added on top of whatever your drug plan charges, so a $40 plan becomes a $77.50 plan in the third bracket. People who are married and file separately fall under a different set of thresholds. Figures come from Medicare's published 2026 cost tables.
What that looks like in practice: say your 2024 MAGI was $100,000 and you took a $15,000 annuity payout that was fully taxable. That puts you at $115,000, just over the first threshold. Your 2026 Part B premium climbs from $202.90 to $284.10, and your drug plan picks up another $14.50 a month. So the payout cost you roughly $1,148 in extra Medicare premiums for the year. Keep the taxable portion under $9,000 and you pay nothing extra.
This means that a person receiving annuity income, from either type, could inadvertently cross into a higher IRMAA bracket and face additional Medicare costs. These extra costs can range from a few hundred to a few thousand dollars per year. If you've experienced a life change that caused a temporary income spike, you may be able to appeal the IRMAA surcharge with help from a Medicare advisor.

My income fluctuates significantly year to year from investment distributions. How can I avoid IRMAA surcharges when I have an unusually high-income year?
Income spikes from investments can definitely trigger IRMAA if we’re not planning ahead.Since Medicare premiums are based on income from two years prior, what I typically recommend is proactive tax planning. If the high-income year was a one-time event, we can file an appeal with the Social Security Administration to request a reduction.
We also look at strategies like spreading out distributions, managing capital gains, and timing Roth conversions carefully so you stay below the IRMAA thresholds whenever possible.
It really comes down to planning ahead so a temporary income spike doesn’t increase your Medicare premiums unnecessarily.
Using Annuities to Plan for Medicare Costs
Despite the potential downside of increasing your Medicare premiums, annuities can still serve as a valuable tool for covering healthcare expenses in retirement. Many retirees rely on the steady, predictable income from annuities to manage the recurring costs associated with Medicare. This includes monthly premiums for Part B and Part D, Medigap plan premiums, and regular out-of-pocket expenses like deductibles and copays.
For individuals who lack a pension or are concerned about market fluctuations affecting their retirement savings, annuities can provide peace of mind by ensuring that healthcare costs are met consistently. Some people also use this income to help pay for services not covered by Original Medicare, such as dental, vision, and hearing care.
To get the most benefit, it's important to carefully consider the timing and structure of annuity payouts. If payments begin during the period used to calculate IRMAA surcharges, they could push your income over the threshold and trigger higher premiums. You can also explore smart tax planning strategies to lower your Medicare costs. Working with a financial advisor can help align your annuity strategy with your Medicare planning, potentially minimizing tax implications and avoiding unexpected costs.

How can I lower my Medicare Part B premium if my income drops after retirement?
If your income drops after retirement, you may be able to lower your Medicare Part B premium by requesting a review of your income. Medicare uses a prior tax year to set premiums, so if your current income is lower due to a qualifying life event—like retirement—you can file an appeal using Form SSA-44 with the Social Security Administration.If approved, your premium can be adjusted to reflect your current, lower income instead of your past earnings, which can significantly reduce what you pay each month.
How Annuities Fit Alongside Medicare, Medigap, and Life Insurance
Health coverage, Medicare, life insurance, and annuities tend to get shopped together, often through the same agent, because one person is frequently licensed to sell all of them. They do very different jobs, though, and only one of them moves your Medicare premiums.
Medicare and Medigap pay your medical bills. A Medicare Supplement plan fills in the deductibles and coinsurance Original Medicare leaves behind, and you pay a monthly premium for it out of pocket. That is exactly the kind of fixed, recurring retirement expense annuity income is good at covering.
Life insurance pays your beneficiaries, and it does not affect your Medicare premiums. Neither the premiums you pay in nor the death benefit your family collects shows up in your MAGI, so a life policy will never push you into an IRMAA bracket. It can still matter to your health planning, since some policies carry riders that help with costs Original Medicare won't cover.
An annuity pays you. That is the whole difference. Because the money lands in your hands as income, it's the one product in this group that can raise what you pay for Part B and Part D.
Should You Use Annuities in Your Medicare Plan?
Whether annuities make sense in your Medicare planning depends on several personal factors:
-
Your current and expected income levels
-
Your health status and likelihood of needing long-term care
-
Your tax situation
-
Whether you plan to enroll in Medicaid later in life
For some, annuities offer peace of mind and predictable income that can comfortably cover Medicare-related expenses. For others, they may trigger unintended costs, particularly through higher premiums. The key is understanding why Medicare should be part of your broader retirement strategy so you can weigh these trade-offs before committing.
A note on Medicaid planning: If you think you may need Medicaid coverage down the road, talk with an elder law attorney or a Medicaid planning specialist before purchasing an annuity. Medicaid's treatment of annuities is complex, highly state-specific, and only certain Medicaid-compliant annuities avoid being counted as assets.
Balance is Key
Annuities can be a helpful financial tool in retirement, but only if used strategically. Their role in Medicare planning is mostly indirect but significant. While they don't provide healthcare coverage themselves, annuities can affect what you pay for that coverage and how you qualify for related programs like Medicaid.
What to do next:
- Pull your 2024 tax return and find your MAGI. That's the number setting your 2026 premiums.
- Ask your annuity carrier for the taxable portion of each payout, not just the gross amount.
- Add the two together and check where the total lands against the brackets above before you take a lump sum or start payments.
- If a one-time life event already pushed your income up, file an appeal instead of paying the surcharge for a full year.
If you're nearing retirement or already enrolled in Medicare, it's worth speaking to a qualified financial advisor and licensed Medicare broker who understands Medicare rules and how annuity income is treated for tax and premium purposes. With proper planning, annuities can complement your Medicare strategy and help you manage healthcare expenses throughout retirement.