Medicare and Employer Insurance: How They Work Together and When to Switch
-
Last Updated September 28, 2026
If you’re turning 65 and still working, you have three questions to sort out: whether you can have Medicare and employer insurance at the same time, which one pays your bills first, and when it makes sense to drop the employer plan entirely. This guide walks through all three, plus the enrollment timing that keeps you from paying a penalty for the rest of your life.
Key takeaways
- You can hold employer coverage and Medicare at the same time. Which one pays first depends on whether your employer has 20 or more employees.
- When your job or your employer coverage ends, you get an 8-month Special Enrollment Period to sign up for Part B without a penalty.
- COBRA is not active employer coverage. That 8-month clock starts when the job ends, not when COBRA runs out.
- Once you enroll in any part of Medicare, you can no longer contribute to an HSA.
Can you have Medicare and employer insurance at the same time?
Yes. If you’re 65 or older and still working, you can keep your employer coverage and enroll in Medicare at the same time — the two plans coordinate, with one paying first and the other paying second. Whether you should enroll right away or delay Part B depends on the size of your employer and whether the employer plan is considered creditable coverage. The rest of this guide walks through the timing, the coordination rules, and what to do when you’re ready to switch fully to Medicare.
A few specifics that trip people up:
- Part A alongside employer coverage: Most people take premium-free Part A at 65 even while working, because it costs nothing and pays second on hospital claims. The one exception is if you’re still contributing to an HSA — see the HSA section below.
- Part B alongside employer coverage: You can absolutely have Medicare Part B and employer insurance at the same time. Whether you should depends on employer size — at a company with fewer than 20 employees, skipping Part B is expensive, because Medicare is supposed to pay first.
- Medicare Advantage alongside employer coverage: This one is different. You can technically be enrolled in a Medicare Advantage plan while covered by an employer group plan, but the two coordinate poorly and you’d be paying for overlapping networks. If you’re keeping employer coverage, Original Medicare is usually the cleaner pairing.

Can I drop my employer health insurance and switch to Medicare instead?
Maybe — but be careful.If you're still working and your employer coverage is considered "creditable" (which most employer plans are), you can delay Medicare without penalty. But if you drop employer coverage and enroll in Medicare, a few things to know:
Part A is usually free — grabbing it at 65 is generally fine.
Part B is the tricky one. Once you drop employer coverage, you typically have an 8-month Special Enrollment Period to sign up without penalty.
HSA conflict — if you're contributing to an HSA, enrolling in any part of Medicare stops that.
Cost comparison — employer plans are often cheaper (especially if your employer subsidizes premiums), so run the numbers before switching.
Bottom line: It's allowed, but whether it's smart depends on your employer's plan cost, your health needs, and whether you're still working. Worth doing a consultation where we can do a side-by-side comparison before you pull the trigger.
Understanding Medicare eligibility and enrollment periods
Medicare Eligibility: If you are a U.S. citizen or permanent resident aged 65 or older, you are eligible for Medicare. Eligibility is not affected by employment status, so you can enroll in Medicare even if you are still working and have health insurance through your employer.
Enrollment Periods:
- Initial Enrollment Period (IEP): This seven-month window begins three months before the month you turn 65, includes your birth month, and ends three months after your birth month. Enrolling during this period gets your coverage started without delay.
- General Enrollment Period (GEP): If you miss your IEP, you can enroll during the GEP from January 1 to March 31 each year. Coverage now begins the month after you sign up (a change from the old July 1 rule), but you may still incur late enrollment penalties.
- Special Enrollment Period (SEP): If you have employer health insurance, you can delay Medicare enrollment without penalty. You have an eight-month SEP to enroll in Medicare once your employment or health coverage ends.
How Medicare works with employer insurance (primary vs. secondary payer)
When you have both Medicare and an employer health plan, one becomes the primary payer and the other pays second. This coordination is what makes it possible to hold both at once without duplicating coverage.
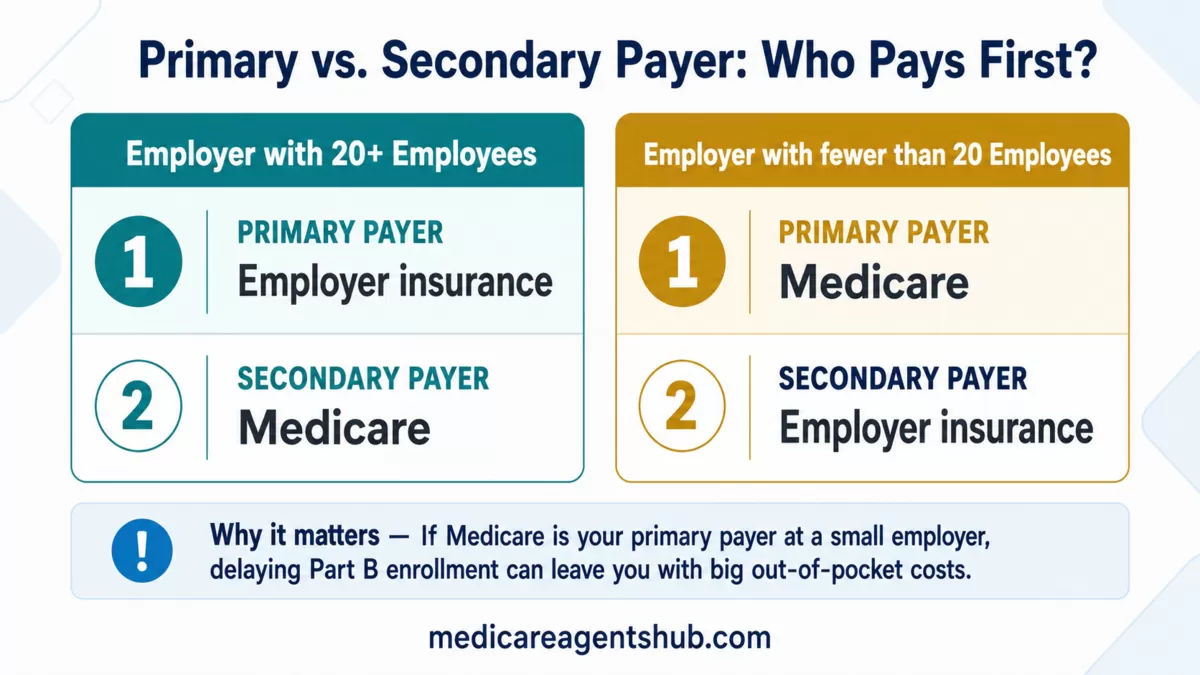
- For companies with 20 or more employees, your employer’s insurance is the primary payer, and Medicare is secondary.
- For companies with fewer than 20 employees, Medicare is the primary payer, and your employer’s insurance is secondary.
Understanding which payer is primary helps manage bills correctly and avoid coverage gaps. If Medicare is your primary payer at a small employer, delaying Part B enrollment can leave you with big out-of-pocket costs, since your employer plan will only pay after Medicare would have.
Can you drop your employer health insurance and go on Medicare?
Yes. If you’re 65 or older, nothing requires you to stay on your employer plan — you can drop it and move to Medicare whether you’re retiring or still working. Dropping employer group coverage is a qualifying event that opens your Special Enrollment Period, so you can enroll in Part B mid-year without waiting for the General Enrollment Period and without a late penalty.
Two things to get right on the timing. First, tell your employer’s benefits administrator your intended end date before you drop, and line up your Part B start date to begin the day after the employer plan ends — a one-month gap is a month of paying full price out of pocket. Second, understand that dropping employer coverage is usually a one-way door: most employer plans will not let you re-enroll until their next open enrollment, and some retiree plans won’t take you back at all.
Whether it makes sense to drop your employer coverage depends on the numbers. Compare your employer plan’s premiums, deductibles, and network against what you’d pay for Part B plus a Medigap policy or Medicare Advantage plan. Family coverage is a big factor — Medicare only covers you, not your spouse or dependents, so if others rely on your employer plan, dropping it has downstream consequences. When Medicare is the better deal, use your Special Enrollment Period to switch cleanly and avoid penalties.

Will Medicare cover everything my current employer plan does?
Traditional Medicare will probably not cover everything your employer insurance covers. Of course that has a lot to do with the benefits offered by the employer plan. Most employer plans have dental insurance and drug insurance embedded in them. Medicare does not cover those things. However, there are so many variables that go into the decision to give up employer benefits and enroll in Medicare that it is impossible to make a decision without seeing all the options available to you. The main things to consider are: Premium, Annual Deductible, MOOP, Provider Networks, co-pays and co-insurance. In addition you need to consider if any other people are dependent on your employer benefits and what are the consequences if they no longer have them. It is best to work with a local broker who will take the time to educate you on all the options and help you make the right decision for your situation.Employer health insurance vs. Medicare: how they compare
Before you drop anything, put the two side by side. The employer plan usually wins on family coverage and out-of-pocket caps; Medicare usually wins on provider access and, for retirees, on total cost.
| Employer health insurance | Medicare | |
|---|---|---|
| Who’s covered | You, your spouse, and dependents | You only — a spouse needs their own coverage |
| Premiums | Employer typically pays a large share of the premium | You pay the full Part B premium, plus more if IRMAA applies |
| Provider access | Limited to the plan’s network | Original Medicare works with any provider that accepts Medicare, nationwide |
| Out-of-pocket maximum | Yes — the plan caps your annual spending | No cap on Original Medicare alone; a Medigap or Medicare Advantage plan supplies one |
| Prescription drugs | Usually built into the plan | Requires a separate Part D plan or a Medicare Advantage plan that includes drugs |
| Dental and vision | Often included or offered as an add-on | Not covered by Original Medicare; some Medicare Advantage plans include it |
| HSA contributions | Allowed if the plan is HSA-qualified | Not allowed once you have any part of Medicare |
| When you can change | Open enrollment or a qualifying life event | Your Initial Enrollment Period, a Special Enrollment Period, or the annual Medicare windows |
The comparison rarely comes out lopsided. Someone covering a spouse and two kids on a subsidized family plan usually stays put; someone single at a 10-person company, where Medicare is already the primary payer, is often paying twice for coverage they’re not getting.
Steps to transition from employer health insurance to Medicare
-
Evaluate Your Health Coverage Needs:
-
Medicare Parts and Additional Coverage:
- Part A (Hospital Insurance): Covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health care.
- Part B (Medical Insurance): Covers outpatient care, doctor visits, preventive services, and medical equipment.
- Part D (Prescription Drug Coverage): Optional coverage for prescription drugs, available through private insurance companies.
- Medigap (Supplemental Insurance): Helps cover out-of-pocket costs not covered by Original Medicare.
-
Decide When to Enroll:
- If you qualify for premium-free Part A, enroll as soon as you are eligible.
- For Part B, consider your employer coverage. If it’s creditable (as good as or better than Medicare), you can delay Part B without penalty. Enroll during your SEP if you lose employer coverage. Be aware that a 2026 rule change affects Medigap enrollment timing for people who defer Part B — knowing about it before you retire can save you from a costly surprise.
-
Notify Your Employer:
- Inform your employer’s benefits administrator of your decision to transition to Medicare for proper coordination of benefits.
-
Enroll in Medicare:
- Enroll in Medicare through the Social Security Administration either online, by phone, or in person at your local Social Security office.

I've been on my employer's health plan but am retiring soon. What should I consider when moving to Medicare?
Retiring and moving from employer coverage to Medicare involves several moving parts, and the decisions you make in the first few months can affect your costs and coverage for years to come. The first thing to understand is that when your employer coverage ends due to retirement, you trigger a Special Enrollment Period that gives you eight months to sign up for Medicare Part B without facing a late enrollment penalty, but most people want to coordinate their start dates carefully so there is no gap in coverage. It is also important to know that COBRA does not count as qualifying coverage for purposes of delaying Medicare, so if you are considering COBRA as a bridge you need to be especially careful about how that interacts with your enrollment deadlines. Beyond the enrollment timing, you will want to think about whether Original Medicare with a Medigap policy and a Part D plan makes more sense for your situation, or whether a Medicare Advantage plan is a better fit, and that decision should factor in your doctors, your medications, your expected healthcare usage, and your budget. If your spouse is younger and still working, there may also be options worth exploring around their employer plan depending on how it coordinates with Medicare. People who have had good employer coverage for years are sometimes surprised by what Medicare does and does not cover, so sitting down with a knowledgeable agent before your retirement date rather than after is the smartest move you can make.Costs associated with Medicare
Part A Costs:
- Most people do not pay a premium for Part A if they or their spouse paid Medicare taxes for at least 10 years.
- There’s a Part A deductible per benefit period, with coinsurance amounts that increase the longer you stay in the hospital. Check the current-year Part A costs on Medicare.gov before you plan.
Part B Costs:
- Part B has a standard monthly premium and an annual deductible, after which you typically pay 20% of the Medicare-approved amount for services. Premium amounts change each year — look them up on Medicare.gov for the current year.
- Higher earners pay more under IRMAA (see below).
Part D and Medigap Costs:
- Premiums for Part D and Medigap plans vary based on the plan and provider. Late enrollment in Part D can incur lifelong penalties — 1% of the national base beneficiary premium for every full month you went without creditable drug coverage, added to your premium for as long as you have Part D.
Important considerations
-
Health Savings Accounts (HSAs):
- You cannot contribute to an HSA if you have any part of Medicare (IRS Publication 969). If you or your spouse has an HSA, plan accordingly before enrolling in Medicare.
-
COBRA and Retiree Insurance:
- COBRA is not considered active employer coverage by Medicare. Your 8-month Special Enrollment Period begins when your employment ends, not when your COBRA ends. Staying on COBRA past that window can trigger late enrollment penalties and gaps in coverage — so if you take COBRA, still enroll in Part B on time.
- Some employers offer retiree health insurance, which may work alongside Medicare. Make sure you understand how retiree insurance coordinates with Medicare.
How the 8-month clock actually runs
Say you retire March 31 and your employer plan ends that day. Your Special Enrollment Period runs April 1 through November 30.
You take COBRA, and it lasts 18 months — well into the following year. The SEP still closes November 30. Sign up for Part B after that and you’re waiting on the General Enrollment Period, sitting through a coverage gap, and paying a Part B penalty for the rest of your life.
Take the COBRA if you want it. Enroll in Part B anyway.
-
IRMAA (Income-Related Monthly Adjustment Amount):
- Higher-income beneficiaries may pay more for Part B and Part D based on their income with this IRMAA fee. Plan for these additional costs.

Is COBRA considered creditable coverage for Medicare, or do I still need to sign up for Part B?
COBRA does not protect you the same way active employer coverage does when it comes to Medicare Part B.If you are 65 or older and your employment ends, your 8-month Special Enrollment Period for Part B begins when the job or active employer coverage ends — even if you elect COBRA afterward. Do not wait until COBRA ends to enroll in Part B.
Prescription coverage is different.
Your COBRA plan may include prescription coverage that Medicare considers creditable, meaning it is expected to pay at least as well as Medicare Part D. The plan is required to tell you whether the drug coverage meets that standard.
If the COBRA drug coverage is creditable, you can generally delay Part D without a late-enrollment penalty while that coverage continues.
If it is not creditable, do not rely on COBRA as your prescription coverage. Once you go 63 days or more without Part D or other creditable drug coverage, you can begin accumulating a Part D late-enrollment penalty. The penalty generally increases for every month you went without creditable coverage and can stay with you for as long as you have Medicare drug coverage.
That is why I would confirm the drug coverage before the employer plan ends. If it is not creditable, use your Medicare enrollment opportunity to get Part D or a Medicare Advantage plan that includes prescription coverage rather than waiting for COBRA to run out. Medicare also provides a Special Enrollment Period when creditable drug coverage is lost or is determined to no longer be creditable.
The simple rule is: COBRA does not stop the Part B clock, and non-creditable COBRA drug coverage does not protect you from the Part D penalty.
Conclusion
Switching from employer health insurance to Medicare requires careful planning and understanding of enrollment periods, costs, and coverage options. By evaluating your needs, coordinating benefits, and making good decisions, you can keep your coverage continuous through the transition.
The rules for switching can get complicated. Find a licensed Medicare agent on MedicareAgentsHub.com for personalized, no-cost help with your transition.