Is Original Medicare Enough? 5 Essential Services It Doesn’t Cover
-
Last Updated October 26, 2026

Reviewed by Brody Crawford
Medicare Agent Licensed in PA, AL, AR & 42 other states
When you turn 65, enrolling in Medicare can feel like a huge relief. You finally have health insurance that helps cover many of the medical costs you might face in retirement. But it’s important to understand what Original Medicare (Parts A and B) actually includes, and just as importantly, what it leaves out.
While Original Medicare provides a solid foundation for your healthcare, it doesn't offer complete protection. When working with Medicare advisors, many retirees are surprised to find they still face significant out-of-pocket costs or need additional coverage for essential services. If you’re planning to rely on Medicare Parts A and B alone, here are five key services it doesn’t cover, and what that could mean for you.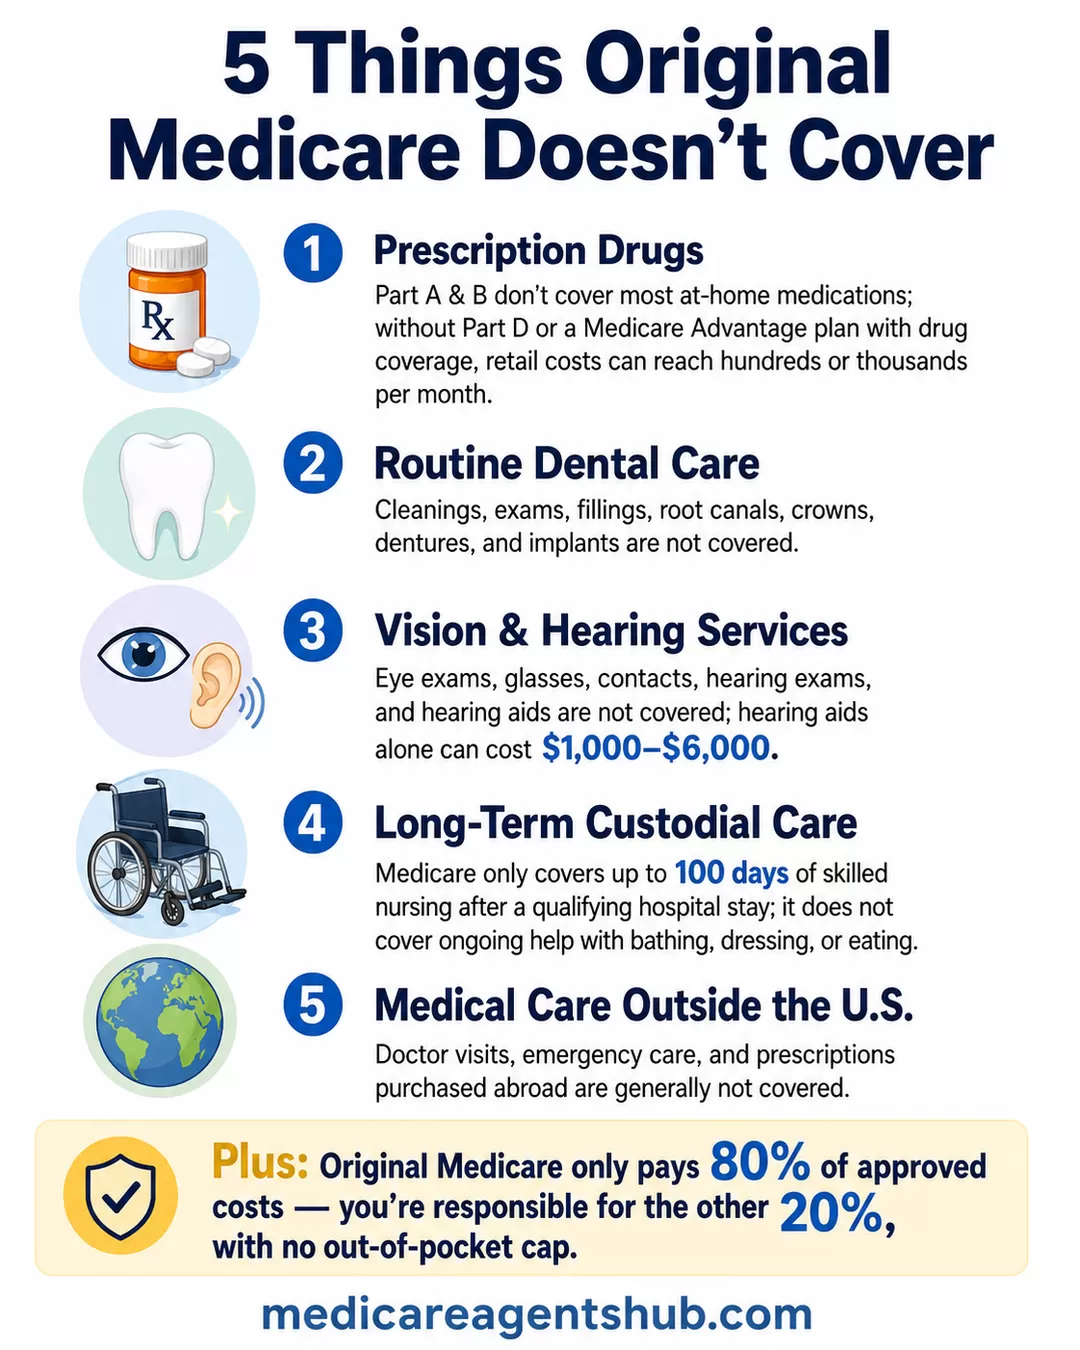
What Original Medicare Actually Covers
Original Medicare, sometimes called traditional Medicare, is the federal program made up of two parts:
-
Part A (hospital insurance) pays for inpatient hospital stays, short-term skilled nursing care after a qualifying hospital admission, hospice, and some home health care.
-
Part B (medical insurance) pays for doctor visits, outpatient care, lab work, durable medical equipment, and preventive screenings like the annual wellness visit, mammograms, and colonoscopies.
That is real coverage, and for hospital and physician care it is strong. What trips people up is everything sitting outside those two buckets, plus the fact that Part B generally pays only 80% of the approved amount. Here are the five gaps that cause the most surprise bills.
5 Things Original Medicare Doesn’t Cover
1. Prescription Drugs
Perhaps the most well-known gap in Original Medicare is prescription drug coverage. Part A covers hospital care, and Part B covers outpatient services like doctor visits and lab work, but neither covers most prescription medications you take at home.
If you need ongoing medications for conditions like high blood pressure, diabetes, or arthritis, you’ll need to enroll in a Part D drug plan or choose a Medicare Advantage (Part C) plan that includes drug coverage. Without one, you could end up paying the full retail price for your prescriptions, which can easily run into hundreds, or even thousands of dollars per month.
Part D plans do have a safety net that Original Medicare lacks. Once your covered drug costs hit $2,100 out of pocket in 2026, you pay nothing more for covered prescriptions the rest of the year. Skip the drug plan and you skip that cap too.

I have multiple medications; how can I ensure my Medicare Part D plan covers them all without breaking the bank?
I recommend you shop with your total yearly out-of-pocket cost as the #1 priority. That means zero in on the combo of premium + copays/coinsurance for your specific drugs over the whole year. That's what really hits your wallet.You can have an agent do this or do it yourself on Medicare.gov's Plan Finder. Plug in your ZIP, list every med (name, strength, how you take it), and it'll show plans that cover them.
Compare by "Estimated Annual Drug Costs" or "Total Out-of-Pocket"—premium plus pharmacy costs for your exact list. Pick the lowest total for you.
Big key step most skip: After you narrow to a couple plans, check pharmacy prices in the tool—costs can swing $50–$200+ per fill just by where you go. List at least 5 nearby ones to compare: Walmart (usually cheap generics), a grocery store pharmacy like Kroger or Publix (great for convenience and often low prices), a big brand like CVS or Walgreens (good selection but watch premiums), maybe Costco if you're a member, and an independent local one if you have a favorite. Run your meds through each—pick the combo of plan + pharmacy that keeps your yearly total lowest.
Plan stars or customer service ratings are nice to glance at, but they don't pay your bills. If two plans cover your meds the same, chase the cheapest total you pay—stars won't cover a big price difference.
2. Routine Dental Care
Original Medicare does not cover routine dental services such as cleanings, exams, fillings, root canals, crowns, dentures, or dental implants. These are treated as non-medical services and are not included in Medicare Parts A or B.
There is one narrow exception. Part A may pay for a dental procedure when it’s medically necessary during a covered hospital stay, like jaw reconstruction after an accident. That’s the exception rather than the rule. The everyday dental care most seniors rely on is entirely out of pocket.
That gap matters more than it sounds, since poor dental health has been linked to infections and heart disease. If you want help covering dental costs, you’ll need to purchase a standalone dental insurance policy or look into a Medicare Advantage plan that includes dental benefits.

Do Medicare Advantage plans include dental coverage?
Yes, most Medicare Advantage plans include dental coverage. While Original Medicare does not cover routine dental care like cleanings and fillings, over 90% of Medicare Advantage plans offer supplemental dental benefits, which range from basic preventive care to more extensive restorative services. The specific dental services covered vary significantly depending on the exact plan and provider you choose.3. Vision and Hearing Services
Vision and hearing care are also missing from Original Medicare. Here’s what that means:
-
Routine eye exams for glasses or contact lenses are not covered
-
Hearing aids are not covered, and neither are the exams to fit them
-
Eyeglasses, contacts, and hearing devices must be paid for out of pocket
Medical eye and ear care works differently. Part B pays for yearly diabetic eye exams, glaucoma tests if you’re at high risk, and diagnostic hearing and balance exams when a doctor orders them to investigate a medical problem. So the testing can be covered while the glasses and hearing aids still aren’t.
This can be especially frustrating since hearing and vision often decline with age. Hearing aids alone can cost $1,000–$6,000 or more, and Medicare won’t help with that expense unless you have a supplemental plan that includes it.
Some Medicare Advantage plans offer limited vision and hearing benefits, but under Original Medicare, you’ll need to budget for these services yourself.

Does Medicare cover hearing aids, or do I have to pay out of pocket?
Original Medicare does not cover hearing aids or routine hearing exams, so you would typically pay out of pocket. Medicare Part B may cover diagnostic hearing tests if ordered by a doctor, but not the hearing aids themselves. Some Medicare Advantage plans offer hearing aid benefits, often with limits on brands, providers, and annual coverage amounts. It’s important to review the specific plan details to understand what is included and what costs you may still have.4. Long-Term Custodial Care
This is one of the most misunderstood gaps in Medicare coverage. While many people assume Medicare will pay for a nursing home or assisted living facility, that’s not usually the case.
Medicare only covers short-term stays in a skilled nursing facility after a qualifying hospital stay (and even then, only up to 100 days). It does not cover custodial care (such as help with bathing, dressing, or eating) if those are the only services you need.
Long-term care that Medicare won’t pay for can be very expensive, especially if it’s needed for months or years. Without long-term care insurance or Medicaid eligibility, you may have to pay for these costs out of pocket. Medicaid is a separate, means-tested program that many families rely on once savings run out, but qualifying takes planning.
5. Medical Care Outside the U.S.
If you’re planning to travel or retire abroad, you should know that Original Medicare offers very little coverage outside the U.S. In most cases, Medicare won't pay for:
-
Doctor visits in other countries
-
Emergency care while traveling
-
Prescription drugs purchased abroad
Some Medigap (Medicare Supplement) plans offer limited foreign travel emergency coverage, and it’s narrower than most people think: typically 80% of costs after a small deductible, capped at $50,000 over your lifetime, and only for emergencies that begin during the first 60 days of a trip. Under Original Medicare alone, you’d need to purchase separate travel insurance or pay entirely out of pocket for international care.
Why Original Medicare Isn’t Enough on Its Own
While Medicare Parts A and B offer reliable coverage for hospital stays, doctor visits, lab work, and preventive care, they leave a lot of common healthcare needs uncovered. The costs for prescription drugs, dental work, vision care, hearing aids, and long-term care can add up quickly and if you’re not prepared, they can eat into your retirement savings fast.
This is why many people choose to enhance their coverage with:
-
Medicare Supplement (Medigap) insurance
-
Part D prescription drug plans
-
Private dental, vision, or hearing policies
Here’s how the three paths stack up against each gap:
| Coverage gap | Original Medicare alone | Medigap (added to Original) | Medicare Advantage (Part C) |
|---|---|---|---|
| Prescription drugs | Not covered | Not covered, you add a separate Part D plan | Usually built into the plan |
| Routine dental | Not covered | Not covered, you buy a standalone policy | Many plans include a limited benefit |
| Vision and hearing | Not covered | Not covered, you buy a standalone policy | Many plans include a limited allowance |
| Long-term custodial care | Not covered | Not covered | Not covered |
| Care outside the U.S. | Almost never covered | Plans C, D, F, G, M, and N include foreign travel emergency coverage | Varies, some plans add limited worldwide emergency care |
| The 20% coinsurance | You pay it, with no annual cap | Picks up most or all of it | Copays instead, with a required annual out-of-pocket maximum |
Notice the one row where every column says no. Long-term custodial care is the gap no Medicare product fills, which is why it catches so many families off guard.
Some beneficiaries also consider add-on products like hospital indemnity, critical illness, and cancer plans to fill gaps that even supplemental coverage may not fully address.
What About Walkers, Wheelchairs, and Home Medical Equipment?
This is the gap people guess wrong in both directions. Part B does cover durable medical equipment (DME) when your doctor documents that you need it at home: walkers and rollators, canes, manual wheelchairs and power scooters, hospital beds, bedside commodes, oxygen equipment, CPAP and BiPAP machines, and blood sugar monitors. You pay the usual 20% coinsurance, and the supplier has to be enrolled in Medicare, so buying the same walker yourself online means paying 100% of it.
What Medicare will not pay for is equipment it considers a convenience or home modification rather than medical care. Medicare's DME rules exclude bathroom safety items like shower chairs, tub benches, and grab bars, along with stair lifts, standard recliners and lift chairs beyond the seat-lift mechanism itself, and most anything bought without a prescription. Those are the purchases families usually end up making out of pocket, often right after a fall or a hospital discharge.
What About Extra Benefits?
You’ve probably seen TV ads promoting over-the-counter allowances, grocery or food cards, and gym memberships like SilverSneakers. None of those come with Original Medicare. They’re extra benefits offered by some Medicare Advantage plans, and they vary widely by carrier and county. If any of these perks matter to you, you’ll want to compare Advantage plans in your ZIP code carefully, since the exact benefits and dollar amounts change every year. Just don’t pick a plan on the extras alone. If the doctor network or drug formulary doesn’t fit, an OTC card or gym membership won’t make up for it.
Each of these options has pros and cons, and the right combination depends on your health, budget, and lifestyle. But one thing is clear: relying on Original Medicare alone leaves serious gaps in your protection.
The Biggest Financial Risk: No Out-of-Pocket Maximum
In addition to these uncovered services, it’s important to know that Original Medicare only pays 80% of approved medical costs. That means you’re responsible for the remaining 20% out of pocket, with no cap on total spending. Unlike employer coverage or Medicare Advantage plans, there is no annual maximum that stops the bleeding once your bills get big. A single serious hospitalization or long chemotherapy course can leave you exposed to tens of thousands of dollars in coinsurance.
To be clear about the two limits people mix up: Medicare has no lifetime dollar limit on your benefits, so it will not cut you off after some total amount has been spent on your care. But it also has no annual limit on what you pay. Your 20% share keeps running for as long as you keep needing care, which is the risk a Medigap plan or a Medicare Advantage plan’s out-of-pocket maximum is designed to cover.
The short video below walks through how that 20% coinsurance actually plays out for someone on Original Medicare:
So even if Medicare does cover a service, like a hospital stay or doctor visit, you’re still on the hook for a portion of the bill unless you have supplemental coverage.

Can you just have A and B and not enroll in anything else and still have good coverage?
Having just Part A and Part B is not advisable because there are still a lot of holes in the coverage. The main hole in coverage would be there is no cap on your Part B coinsurance. Part B covers 80% of the medical bill, and you’re responsible for the 20% with no cap on the dollar amount. When you start looking at huge procedures that can cost many hundreds of thousands of dollars, and you’re responsible for 20% of however high the bill goes, that’s the biggest hole in coverage.So, Is Original Medicare Enough?
Original Medicare is a strong starting point for healthcare in retirement, but it’s not comprehensive. Understanding what it doesn’t cover, especially when it comes to prescriptions, dental, vision, hearing, long-term care, and international travel can help you avoid unexpected bills and make smarter choices about your healthcare planning.
For most people the honest answer is no, not by itself. Original Medicare is the foundation, and then you decide what else you need on top of Part A and Part B. If you're unsure which additional plans you may need, a licensed agent can look at your prescriptions, your doctors, and your budget before you commit to anything. You can tell us what you need and get matched with an agent, or browse Medicare agents near you and reach out directly. There’s no cost or obligation to talk with anyone in the directory. The better you understand your options, the better protected you'll be, both medically and financially.
You can also get free, unbiased Medicare help from your State Health Insurance Assistance Program (SHIP), or by calling 1-800-MEDICARE.