Helping Clients Understand Their ANOC: A Resource for Insurance Agents
-
Last Updated October 15, 2026
Each fall, Medicare Advantage and Part D plan members receive a document called the Annual Notice of Change (ANOC). It’s one of the most important communications they’ll get all year. Unfortunately, many beneficiaries ignore it, skim it, or misunderstand it altogether.
As an insurance agent, a key part of the job is guiding clients through the fine print. The ANOC is where much of that fine print lives. Walk them through it properly and they head into the Medicare Annual Enrollment Period (AEP) knowing exactly what changed and what to do about it.
What Is an ANOC?
The ANOC is a required document that Medicare Advantage (MA) and Part D plans send to their members by September 30 each year. It details any changes in:
-
Benefits
-
Costs (including premiums, copays, and deductibles)
-
Drug coverage and formularies
-
Provider networks
These changes go into effect January 1 of the following year.
Why Clients Struggle With It
Most clients don’t read their ANOC thoroughly, if they open it at all. The document tends to be lengthy and filled with complex insurance jargon, which makes it intimidating and easy to ignore. On top of that, many clients confuse it with other similar mailings, like the Evidence of Coverage (EOC), and assume it’s just more paperwork. There's also a common belief that if the plan is still active, nothing important has changed and no action is necessary. Unfortunately, this mindset can lead to overlooked cost increases, new restrictions, or changes in drug coverage or provider networks that could significantly impact their care, often not discovered until the new year rolls around and it’s too late to make changes.
Your Role: Make It Simple
Here’s how you can break the ANOC down for clients in a way that’s easy to understand and act on:
1. Start With the Basics
Explain what the ANOC is and why it matters, in plain English.
“This is the document that tells you if your plan is changing next year. It could mean different prices, different doctors, or changes to what’s covered.”
2. Zero In on Key Sections
Help clients focus on the most impactful parts:
-
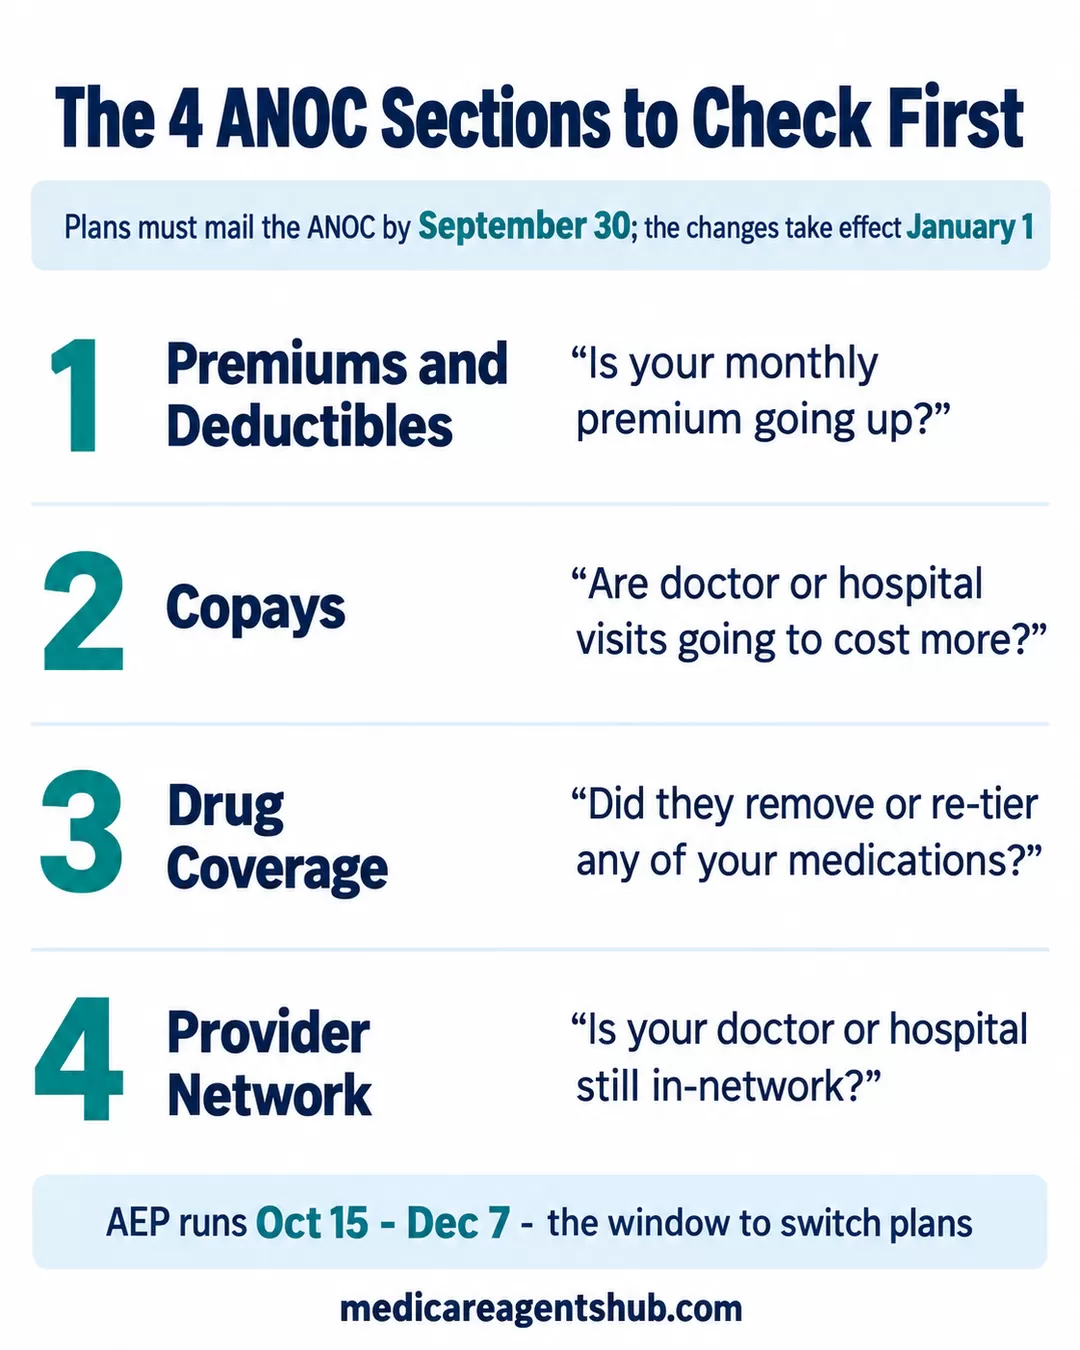
Premiums and Deductibles – “Is your monthly premium going up?”
-
Copays – “Are doctor or hospital visits going to cost more?”
-
Drug Coverage – “Did they remove or re-tier any of your medications?”
-
Provider Network – “Is your doctor or hospital still in-network?”
You can even use a simple comparison chart to make changes clearer:
| Plan feature | 2026 plan | 2027 plan | Change |
|---|---|---|---|
| Monthly premium | $0 | $15 | Up $15 |
| Primary care visit | $10 copay | $20 copay | Up $10 |
| Tier 2 drug copay | $7 | $10 | Up $3 |
| Deductible | $150 | $200 | Up $50 |
Figures above are illustrative. Always point clients back to their own plan documents for the real numbers.
3. Ask Targeted Questions
Don’t just go through the ANOC line by line. Ask specific questions that tie changes to their daily life:
“Do you still take these medications?”
“How often do you visit your specialist?”
“Has your doctor or pharmacy changed recently?”
This helps connect the dots between plan changes and real-world impact.
Start the Conversation in September
The ANOC should kick off your client outreach in September or early October. Waiting until AEP (Oct 15–Dec 7) to discuss plan changes can limit their options.
One compliance note before you start booking: if a review is going to move past the client’s current plan into comparing other options, that’s a marketing appointment, and your Scope of Appointment needs to be documented before you get into plan-specific benefits. The timing requirements here have moved around in recent years, so confirm what applies with your carrier or FMO and check CMS’s managed care marketing guidance before AEP opens.
Consider these strategies:
-
💬 Send client reminders: Let clients know to expect the ANOC in the mail and ask them to keep it. For a deeper dive, see our guide on using the ANOC to guide client conversations.
-
👥 Offer ANOC reviews: Schedule short calls or meetings to walk through the key points.
-
📄 Prepare helpful materials: Comparison charts, FAQs, and simple “What Changed?” summaries go a long way.
Frequently Asked Questions
What’s the difference between the ANOC and the Evidence of Coverage (EOC)?
The ANOC is a short summary of what’s changing for the coming plan year. The EOC is the full contract that explains how the plan works in detail. Clients tend to open the ANOC first because it’s shorter and focused on what’s new.
What should I tell a client who says they never received their ANOC?
Have them check their plan’s member portal or call member services. Most carriers also post it in the member portal, and nearly all will resend a copy on request. If it still doesn’t turn up, walk them through the plan changes yourself using the carrier’s renewal packet.
Can a client stay on their plan if they don’t like the changes?
Yes. If they take no action, they’re auto-renewed into the updated plan on January 1. If the changes don’t work for them, AEP (Oct 15–Dec 7) is the window to switch to something better.
Wrap-Up: Keep It Client-Focused
An ANOC review comes down to making sure the client is in the right plan for the year ahead. Simplify the language and flag what actually changed, and a confusing government document becomes one of your better tools for client trust and retention.
Clients who understand their coverage make a real decision instead of defaulting into one. That matters most when they’re navigating life changes, and those are the clients who stay with the agent who helped them sort it out.